🚨 The AI infrastructure boom may be much bigger than the market realizes.
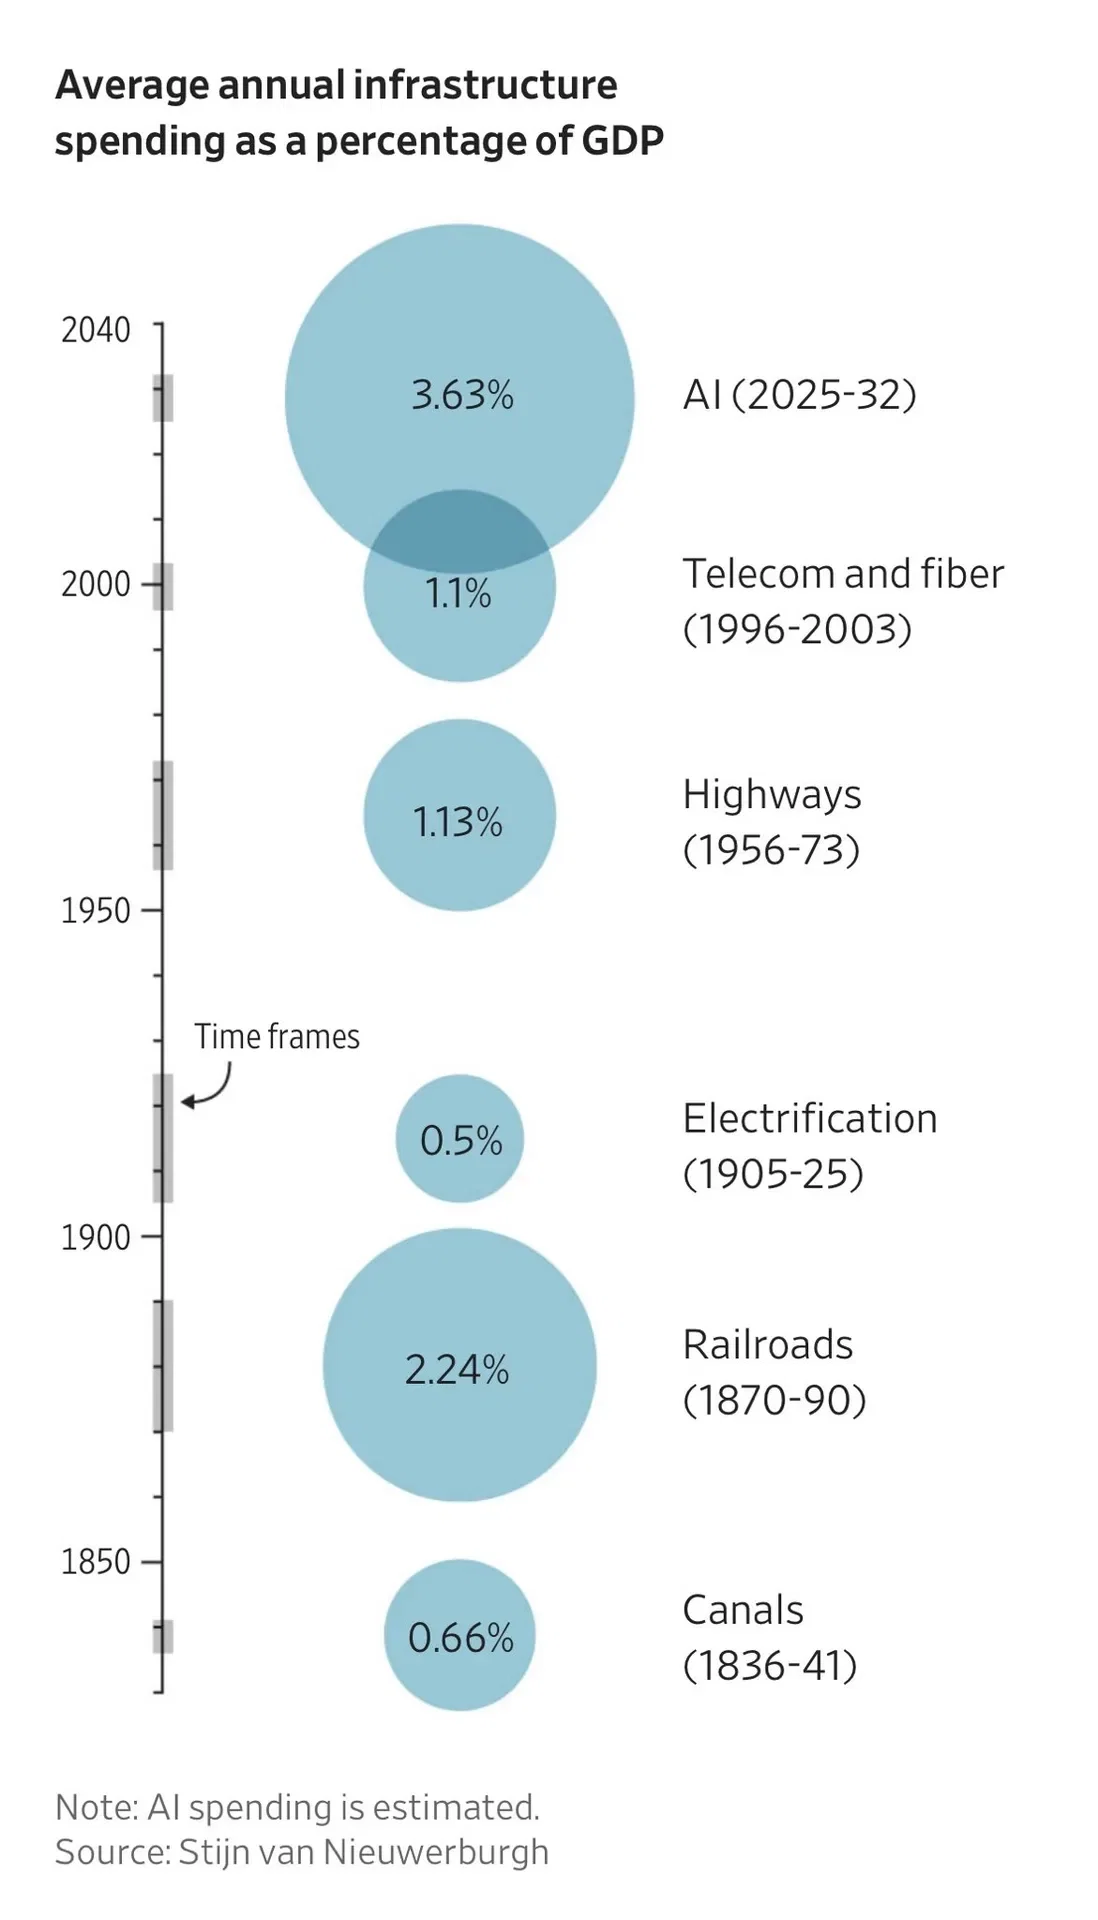
New estimates cited in the post suggest total investment in data centers and related AI infrastructure could reach $10.3 TRILLION between 2025 and 2032.
That would translate into roughly 3.6% of GDP per year.
For perspective, the chart compares average annual infrastructure spending:
🤖 AI infrastructure (2025–32): 3.63% of GDP
🚂 Railroads (1870–90): 2.24%
🛣️ Highways (1956–73): 1.13%
🌐 Telecom & fiber (1996–2003): 1.1%
⚡ Electrification (1905–25): 0.5%
If these estimates are anywhere close to reality, AI isn't simply another software cycle.
It's becoming an infrastructure supercycle.
And that has investment implications far beyond the companies building AI models.
The opportunity expands across the entire physical AI ecosystem:
🔹 Chips & accelerated computing: $NVDA $AMD $AVGO
🔹 Data-center infrastructure: $VRT $ETN
🔹 Power generation & grid investment: $GEV $CEG
🔹 Engineering & infrastructure: $ACM
🔹 Cloud hyperscalers: $MSFT $AMZN $GOOGL $META
The AI race increasingly isn't just about who has the best model.
It's about who can provide the compute, electricity, cooling, networking, buildings and infrastructure required to run AI at massive scale.
If this capex cycle develops as projected, some of the biggest winners from AI may ultimately be the companies building the infrastructure underneath it.
That's one of the themes I'm watching closely in my portfolio.
#AI #ArtificialIntelligence #DataCenters #Infrastructure #Investing #Stocks #Semiconductors #Energy #Technology #Markets